Goodluck Defence Merger with Goodluck India: What Shareholders Should Know
Published: 6 min read
Goodluck Defence’s proposed merger with Goodluck India has in-principle board approval, but shareholders’ exchange terms remain unresolved. Goodluck India’s 28 October filing said the detailed terms were still under evaluation. Neither the 12 October announcement nor the 28 October update specifies a swap ratio, merger record date or confirmed conversion timetable. Source: Goodluck India’s 28 October 2026 filing.
For an existing holder, the important question is what they would receive for their Goodluck Defence shares and when any resulting securities could be traded. Those terms would be set out in the scheme, the detailed restructuring document covering consideration and implementation conditions.
Three points matter when reading the announcement:
- A subsidiary holding and a holding in its listed parent are different investments.
- A previous fundraising price does not guarantee the value offered in a merger.
- Potential access to listed shares depends on the final scheme and implementation; it is not an immediate exit facility.
What has Goodluck India proposed?
On 12 October 2026, Goodluck India Limited expanded its proposed restructuring to include Goodluck Defence and Aerospace Limited, alongside Goodluck Green Energy Limited, for amalgamation with and into Goodluck India. Goodluck Defence is the group’s defence manufacturing subsidiary.
Goodluck India is the listed parent, whose existing business includes manufacturing precision-engineered steel products. Source: Goodluck India’s 28 October 2026 filing.
The company described the proposed consolidation as a way to simplify its structure and align its businesses and stakeholders. Those are the company’s objectives. Whether the terms benefit an individual shareholder will depend on the scheme.
Date | Development | What it establishes |
11 July 2026 | Board gave in-principle approval to restructuring involving Goodluck Green Energy. | The earlier scope of the proposal. |
12 October 2026 | Board widened that scope to include Goodluck Defence. | Preliminary approval to pursue the expanded proposal. |
28 October 2026 | Company said detailed terms remained under evaluation. | Shareholder economics and implementation details were still unresolved in that update. |
Sources: Goodluck India board disclosures dated 11 July, 12 October and 28 October 2026.
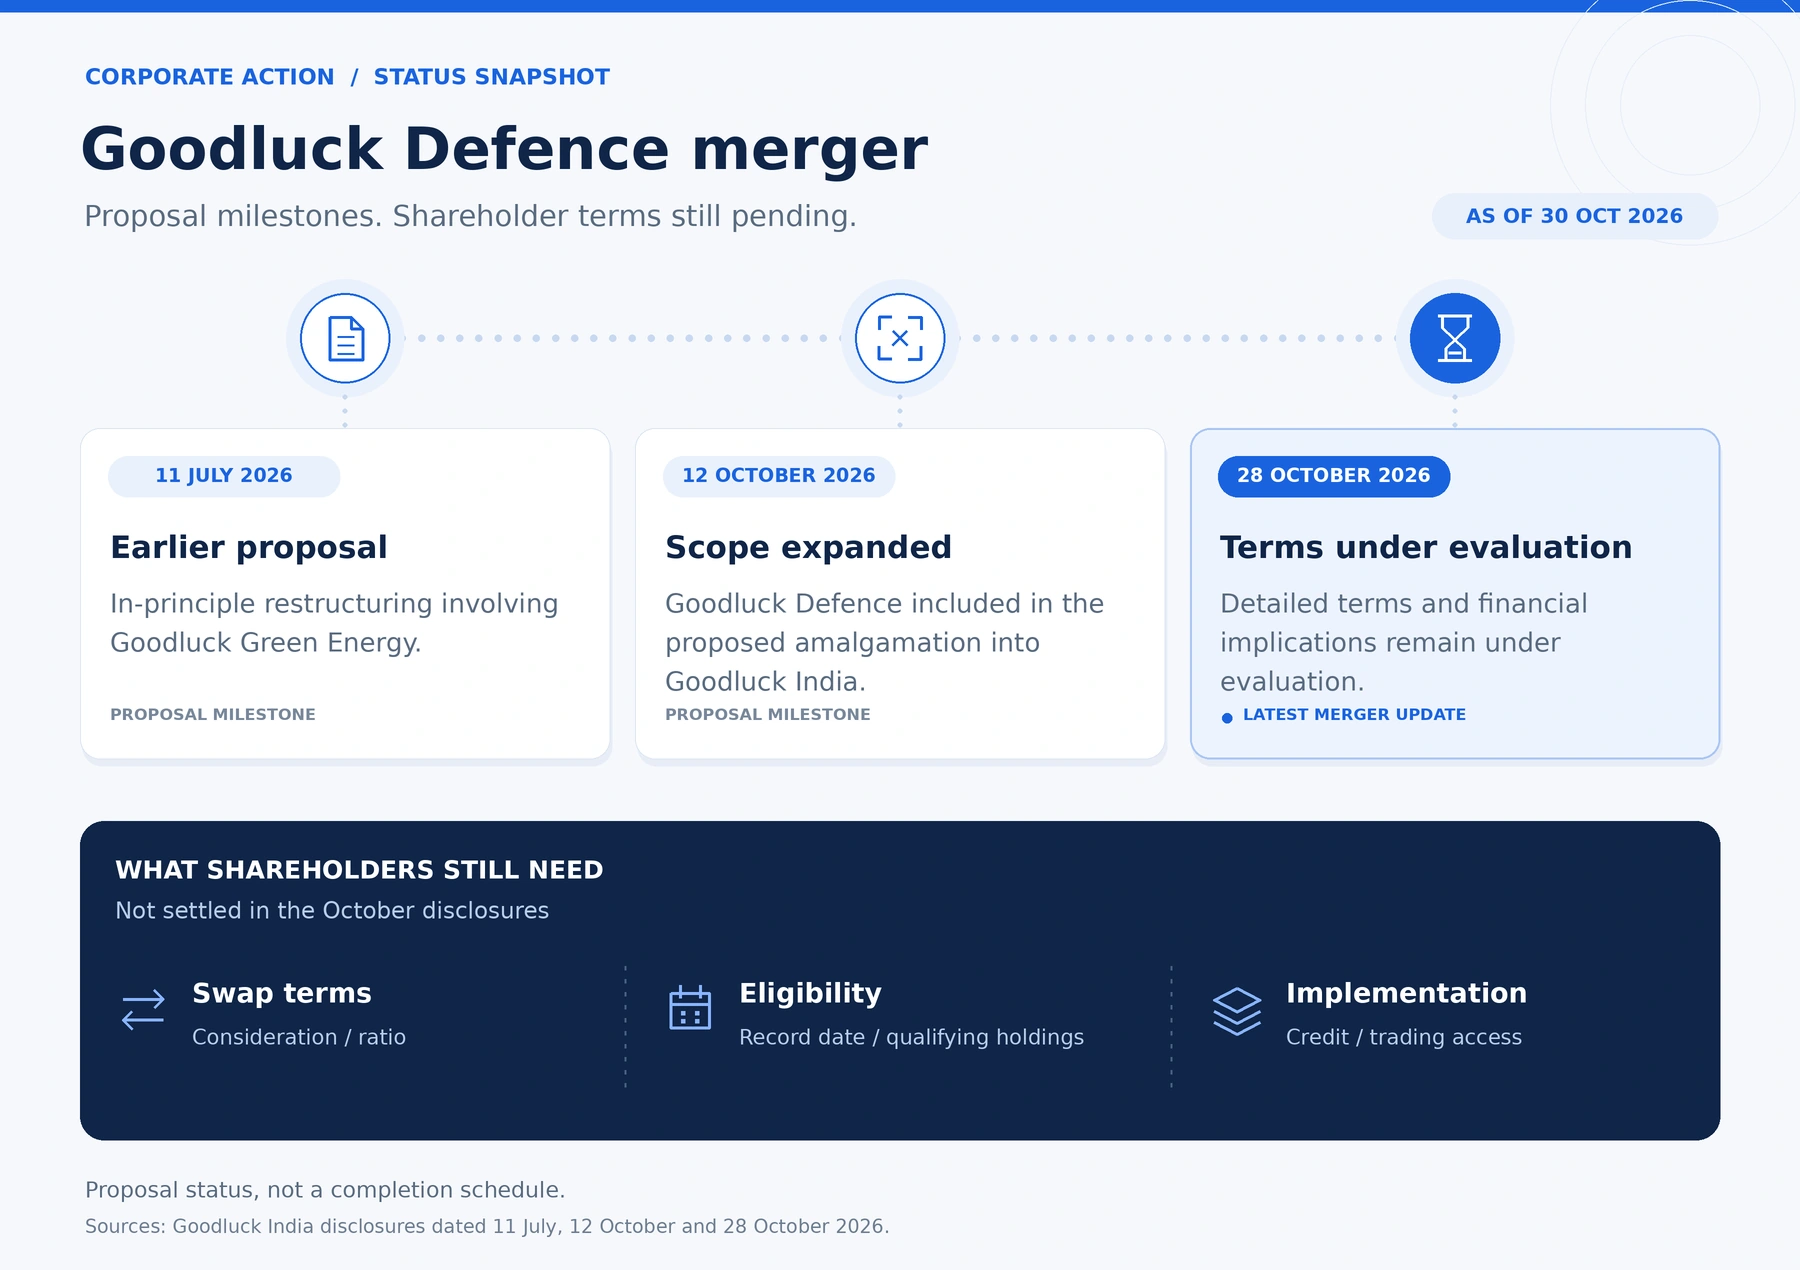
Proposal status as of 30 October 2026; detailed terms pending. Sources: Goodluck India disclosures dated 11 July, 12 October and 28 October 2026.
Why outside Goodluck Defence shareholders matter
Goodluck Defence is not a wholly owned subsidiary. Goodluck India’s September allotment disclosure provides the relevant dated ownership snapshot:
Item | Disclosed position |
New Goodluck Defence equity shares allotted | 73,60,000 |
Issue price per share | ₹375, including ₹365 premium |
Amount raised | ₹276 crore |
Goodluck India’s holding following the issue | 69.08% of Goodluck Defence’s equity capital |
Source: Goodluck India disclosure dated 27 September 2026. These are historical allotment terms, not a current unlisted-share quote or merger consideration.
The detailed scheme will need to explain the proposed treatment of those outside holdings. That treatment is central to understanding what an existing Goodluck Defence shareholder might receive.
Has a Goodluck Defence share-swap ratio been announced?
The 12 October announcement and the merger update in the 28 October filing do not specify a share-swap ratio. The exact consideration for Goodluck Defence shareholders remains a question for the detailed scheme. Sources: 12 October announcement and 28 October update.
A swap ratio describes how many shares in the receiving company a holder gets in exchange for their existing shares. If the eventual scheme uses an equity exchange, both that ratio and the value of the shares received would affect the holder’s economic outcome. Fractional entitlements would also need to be addressed by the scheme.
The ₹375 fundraising price is useful historical context, but it does not establish a minimum merger value. Nor can a ratio be worked out from the two companies’ face values or a movement in Goodluck India’s market price.
Goodluck India’s separate 2:1 bonus action should also not be mistaken for a Goodluck Defence exchange ratio. The July board disclosure treated the bonus and restructuring as separate matters. Source: 11 July 2026 board outcome.
What could change for shareholders?
If you hold Goodluck Defence shares
If an approved scheme exchanges your holding for Goodluck India shares, you would hold shares in a company that includes the parent’s steel and engineering operations as well as the defence business. The final consideration, eligibility and treatment of your existing shares would come from that scheme.
That distinction matters even if defence is the main reason you invested. A broader company’s share price reflects its combined businesses, liabilities, capital requirements and market expectations.
If you hold Goodluck India shares
If new parent shares are issued to outside shareholders of the merging entities, the parent’s share count and existing holders’ percentage ownership could change. A dilution estimate requires the final consideration and capital structure; a minority holding in the subsidiary cannot simply be translated into the same percentage of the parent.
For both groups, the useful comparison will be the ownership and business exposure received under the scheme, alongside the value attributed to each entity.
Does the merger replace the earlier IPO plan?
A proposed amalgamation into an existing listed parent is a different route from a standalone Goodluck Defence IPO. In a November 2025 earnings call, management had discussed an IPO as its thinking at that time. That historical intention should be read alongside the newer restructuring proposal. Source: company transcript of the 10 November 2025 call, filed 14 November.
The merger announcements do not confirm a formal cancellation or withdrawal of the earlier IPO plan. Neither a standalone Goodluck Defence IPO nor receipt of listed parent shares should be treated as a settled outcome.
What should shareholders watch next?
The next useful documents are the detailed scheme and its supporting disclosures. They should be assessed for consideration, valuation basis, eligibility, approvals and implementation conditions.
SEBI’s scheme framework distinguishes a registered valuer’s report from a separate fairness opinion by an independent SEBI-registered merchant banker. It also addresses exchange review and shareholder disclosures. The applicable rules and the actual scheme will govern the process for this transaction. Source: SEBI’s Scheme of Arrangement Master Circular.
Document or notice to watch | Shareholder question it would help answer |
Board-approved detailed scheme and valuation disclosures | What consideration is proposed, and on what basis? |
Applicable exchange, shareholder, creditor and tribunal documents | Which approvals and conditions apply, and what has been completed? |
Record-date and entitlement notices | Which holdings qualify, and how will fractions or special cases be handled? |
Effectiveness, allotment, credit and trading notices | When does the scheme take effect, and when can any new shares actually be dealt in? |
This is a monitoring checklist, not an announced Goodluck timetable. The precise process may include conditions or exemptions that must be read in the operative documents.
Keep your holding statement and acquisition records available, and follow notices through the company’s shareholder-information page and official exchange disclosures. These are general preparation suggestions, not a company-issued conversion instruction. Any form, payment request or deadline should be checked against an official notice.
For current indicative pricing and transaction enquiries, see the Goodluck Defence & Aerospace unlisted shares page.
Sources and scope
The corporate-action evidence is Goodluck India’s July board outcome, September allotment disclosure, 12 October announcement and 28 October update. Historical IPO commentary and general process sources are linked beside the relevant passages.
Information cutoff: 30 October 2026. A check for newer company disclosures did not identify final merger terms. This article explains the announced proposal and its conditional implications; it does not confirm an individual shareholder’s entitlement.
Disclosure
Unlisted Valley facilitates unlisted-share transactions and has a commercial interest in enquiries generated through this website. This article is for information and education, not investment, legal or tax advice. It does not recommend buying or selling either company’s shares or guarantee merger completion, liquidity or returns.